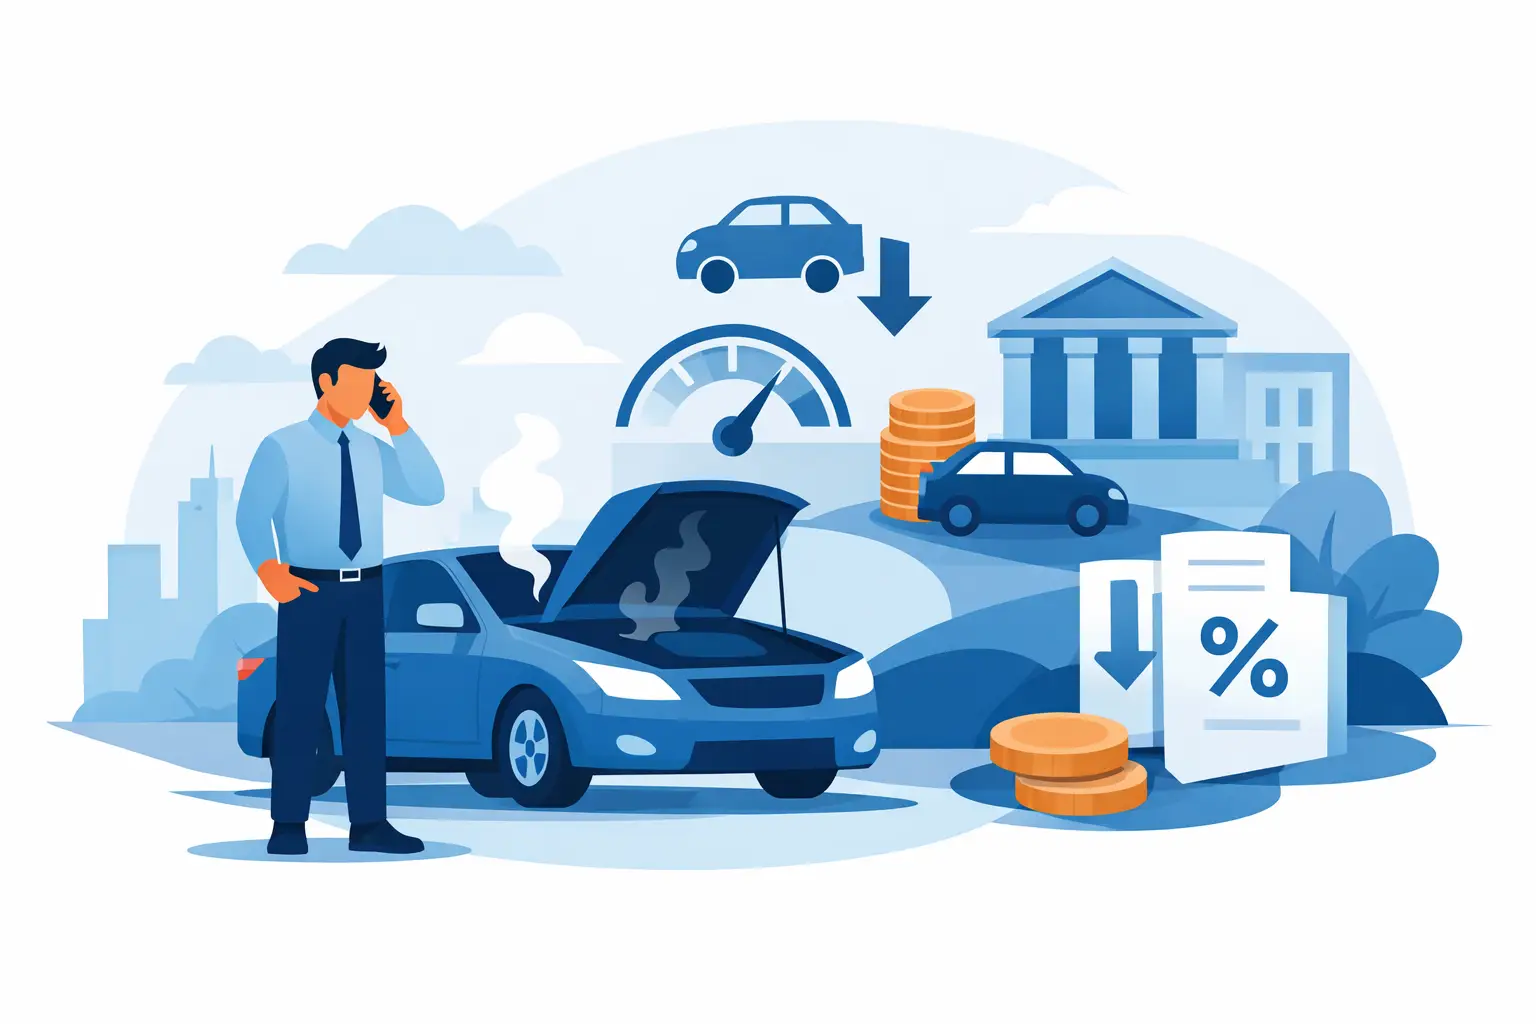
A customer’s vehicle is in the service lane with a failed transmission, a major engine issue, or collision damage. Their transportation has stopped, but the payment due date has not. So, does a breakdown affect loan payments? In most cases, no. The borrower or lessee remains responsible for making scheduled payments even when the vehicle cannot be driven.
That disconnect creates a real financial pressure point for customers and a portfolio-performance concern for lenders, lessors, and dealerships. A breakdown can turn a reliable payer into a customer choosing between a repair bill, alternate transportation, and a monthly vehicle obligation. The payment itself does not automatically pause. The customer’s ability and willingness to keep it current may.
Does a Breakdown Affect Loan Payments Under a Typical Contract?
A vehicle loan is a financing agreement, not a promise that the vehicle will operate without interruption. Unless the finance contract, lease agreement, warranty, service contract, or another separate protection product specifically provides payment relief, a mechanical breakdown does not cancel or defer the payment obligation.
The same principle generally applies after an accident. Insurance may address covered physical damage, subject to deductibles, limits, and claim timing, but collision coverage is not designed to reimburse a monthly loan or lease payment simply because the customer is without a vehicle. Warranty coverage may pay for a qualifying repair, yet it typically does not cover the borrower’s payment while the vehicle is inoperable.
There are exceptions, but they are contract-specific. A lender may offer a hardship accommodation. A lease may have unique provisions. A manufacturer program may provide temporary transportation. None of those possibilities should be presented as an automatic payment holiday. Customers need a clear message: contact the finance company early, continue making payments when possible, and review the exact terms of every applicable agreement.
Why Repair Downtime Can Become a Payment Problem
A repair event often produces more than one expense at the same time. The customer may face a deductible, a repair not covered by warranty, towing charges, rideshare costs, rental expenses, and lost work time. Even if the repair is covered, a lengthy parts delay can leave the household paying for transportation while the financed vehicle sits at the shop.
For a customer with limited monthly margin, that is where payment continuity becomes vulnerable. The payment was affordable when the vehicle was working. It becomes harder when the customer must fund a second way to get to work, school, medical appointments, or family obligations.
This is not just a consumer hardship issue. It is an operational issue for the automotive finance ecosystem. Missed or delayed payments can lead to collection activity, increased servicing costs, customer dissatisfaction, and avoidable damage to a relationship that may otherwise have produced repeat financing, service revenue, and referrals.
A customer who feels abandoned during a breakdown is less likely to view the original dealer, lender, or lessor as a long-term partner. Conversely, a customer who receives practical support during a disruptive event has a stronger reason to return for service and their next vehicle.
What Dealers and Finance Partners Should Explain at Delivery
The delivery conversation is the right time to set expectations. F&I teams should avoid vague reassurance that a warranty or insurance policy will “take care of everything.” Buyers should understand what their loan payment covers, what their warranty may cover, and what expenses can still fall on them if their vehicle becomes unusable.
A clear conversation should establish three points. First, the monthly payment remains due under the financing or lease agreement unless a separate provider approves a change. Second, the customer should notify the finance company promptly if a breakdown creates a hardship. Third, protection products should be explained according to their actual benefits and limitations, not treated as interchangeable.
This clarity protects everyone. It helps customers make informed decisions, reduces post-sale confusion, and gives the dealership a more credible ownership-support story. It also creates a better foundation for ancillary products that are specifically built around the gap between vehicle downtime and payment responsibility.
The Gap Between Repair Coverage and Payment Continuity
Many dealerships already offer products designed to address a portion of the breakdown experience. A manufacturer warranty, vehicle service contract, GAP coverage, roadside assistance plan, or physical-damage policy can each have value. But they answer different questions.
A warranty or service contract may help with an eligible mechanical repair. GAP can address a balance deficiency after a covered total loss. Roadside assistance can help get the vehicle to a repair facility. Insurance may fund a covered loss. Yet none of these benefits necessarily replaces the customer’s monthly payment while a covered event has taken the vehicle out of service.
That is the gap finance and retail partners should evaluate carefully. The issue is not whether existing products are useful. The issue is whether the customer has meaningful support when the payment remains due and the vehicle is unavailable.
Car payment reimbursement memberships are designed to address that specific disruption, subject to the program terms and covered-event requirements. The product category gives dealers, lenders, and lessors a way to provide practical payment-focused relief rather than asking customers to absorb every consequence of downtime alone.
A Revenue Opportunity That Also Supports Retention
For automotive businesses, a well-positioned payment reimbursement membership can do more than add an aftermarket line item. It can support a more resilient customer relationship at the moment that relationship is most likely to be tested.
The commercial case is straightforward. A differentiated membership can create additional revenue per transaction while giving sales and F&I teams a benefit customers can understand: if a covered event makes the vehicle unusable, the program may reimburse the monthly vehicle payment under its terms. Some programs may also provide defined immediate travel or miscellaneous-expense benefits and support toward a replacement vehicle after a qualifying total loss.
CPR For Cars was built around this payment-continuity opportunity. For participating automotive finance and retail partners, the membership is positioned as a non-insurance protection product that can help customers manage covered disruptions while supporting retention, service-center return traffic, and backend revenue.
The product must still be sold responsibly. Teams should explain eligibility, reimbursement limits, waiting periods if applicable, documentation requirements, exclusions, and the difference between membership benefits and insurance coverage. Clear disclosures do not weaken the sale. They build trust and reduce the chance that a customer expects a benefit that was never part of the agreement.
How to Position the Conversation Without Creating Confusion
The strongest presentation starts with the customer’s real risk, not a fear-based script. Ask a simple question: if your vehicle were undrivable for an extended period, could you comfortably keep making this payment while arranging other transportation?
That question is relevant across credit tiers. Prime customers may have savings but still dislike a sudden duplicate transportation expense. Near-prime customers may have less flexibility. Buy-here-pay-here customers can be especially exposed because reliable transportation often directly supports their ability to work and make payments.
Then explain the distinction in plain language. Mechanical coverage may help repair the vehicle. Insurance may help with covered damage. A payment reimbursement membership is intended to help with the vehicle payment after a qualifying covered event. Each product has a separate job.
For lender and lessor partners, the discussion can be equally direct. Payment disruption is not always a credit-quality issue. Sometimes it is a temporary transportation and cash-flow problem triggered by an unusable vehicle. A customer-care benefit that addresses that moment can strengthen goodwill without changing the underlying finance contract.
Build the Program Into the Ownership Experience
The value of a payment-continuity product does not end at signing. Dealers should ensure customers know where their membership information is stored, whom to contact when a covered event occurs, and what documentation may be needed. A service advisor who recognizes the membership can reinforce the dealership’s commitment and help direct the customer to the correct claims or support process.
Internal alignment matters as well. F&I, service, collections, and customer-care teams should use consistent language. If the service department tells a customer that a repair is covered, while the finance office implied that all payments would stop, the dealership has created confusion that no product can fix.
A breakdown does not usually change the customer’s loan payment obligation. What it changes is the customer’s financial reality while their vehicle is out of service. Automotive businesses that address that reality can protect customers, preserve payment performance, and give buyers a compelling reason to keep the relationship close when the next service visit or vehicle purchase arrives.


Leave A Comment