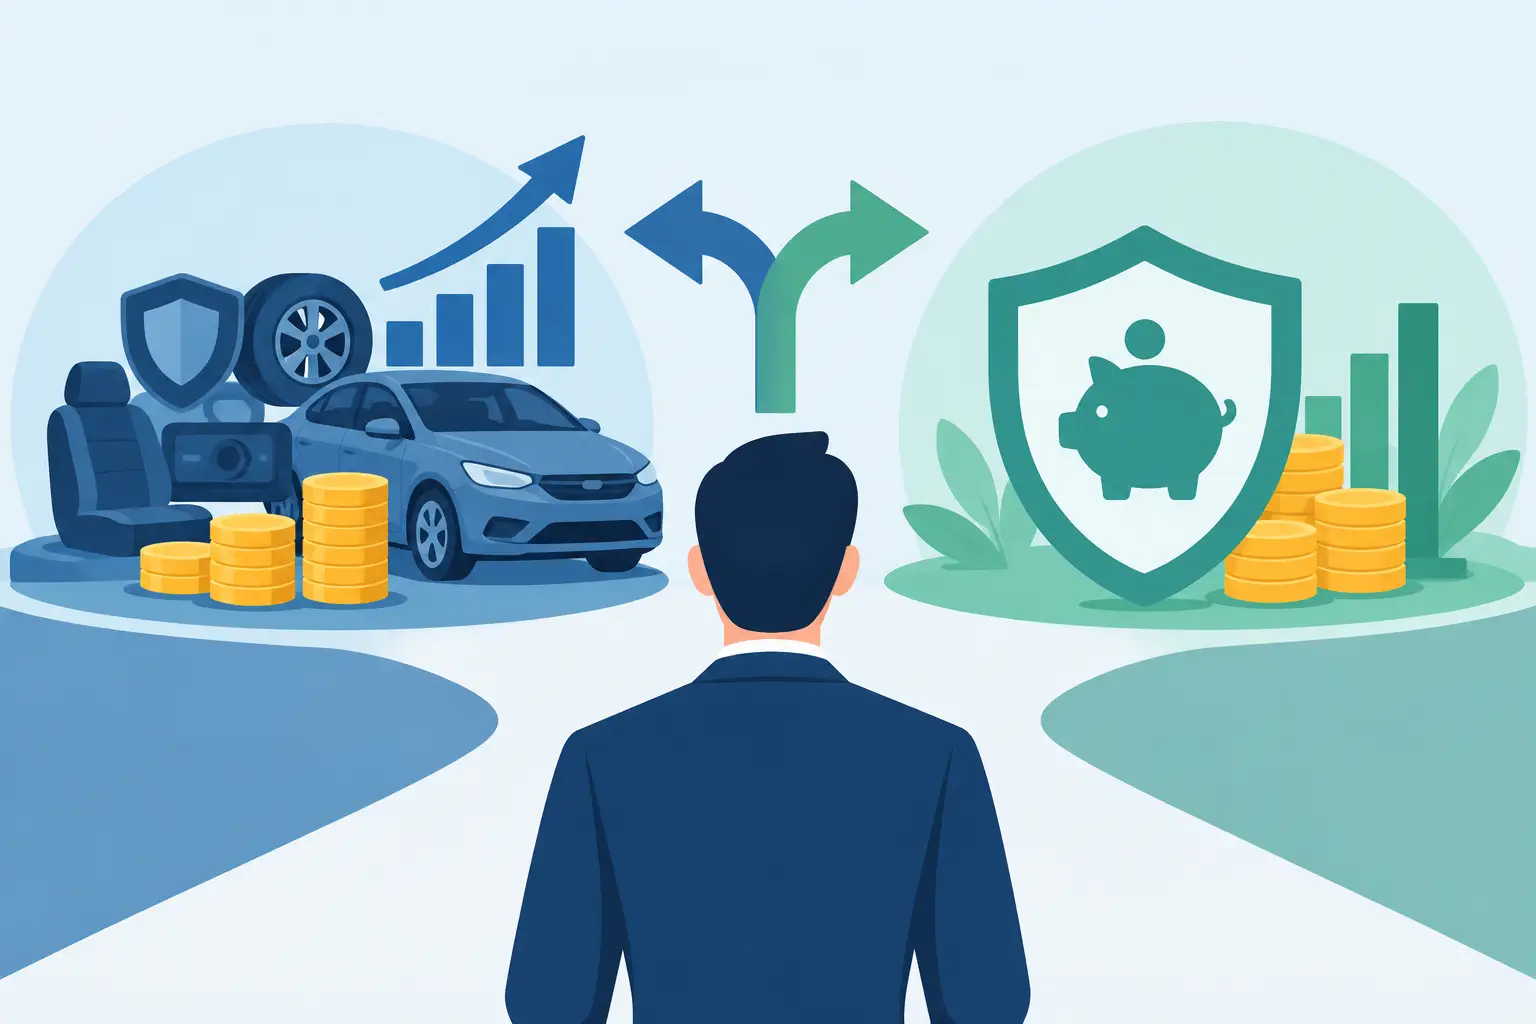
A customer misses work after a breakdown, needs transportation, and suddenly has a repair bill competing with a car payment. For a BHPH operation, that one event can become a collection problem, a reserve expense, or a preventable loss of customer goodwill. That is the real business question behind BHPH add ons versus reserves: should the dealership set money aside to absorb risk after it happens, or offer products that create revenue while helping customers handle disruption?
The strongest answer is rarely an either-or decision. Reserves remain necessary for a healthy BHPH portfolio. But reserves do not generate income, differentiate the dealership, or give the customer a reason to stay engaged when ownership gets difficult. The right add-on strategy can help do all three, provided the product is relevant, properly disclosed, priced fairly, and supported by a disciplined sales process.
What Reserves Do for a BHPH Portfolio
A reserve is money the dealership retains to cover expected and unexpected portfolio costs. Depending on the operation, that may include credit losses, repossession expenses, repairs, charge-offs, legal costs, payment extensions, or customer accommodations. It is a financial safeguard, not a customer-facing benefit.
Every BHPH dealer needs reserves because delinquency and loss are part of the model. A dealership that treats every collected payment as spendable cash can quickly find itself short when several accounts go sideways at once. Sound reserves protect operating stability, support cleaner financial reporting, and keep a temporary collection issue from becoming a cash-flow crisis.
The limitation is just as clear: a reserve sits on the balance sheet waiting for a loss event. It does not increase gross profit per retail installment sale. It does not improve the customer ownership experience. It does not make a borrower more likely to return for service, trade in, or recommend the dealership to family members.
Reserves are essential protection for the dealership. They are not a growth plan.
How BHPH Add Ons Create More Than Revenue
The right BHPH add-on is designed around a real ownership problem. Customers who buy through a BHPH dealership often have little room in their monthly budget for an unexpected repair, accident-related disruption, or transportation emergency. When their vehicle is unusable, the pressure can quickly affect payment behavior.
A well-matched ancillary product gives the dealership an opportunity to address that risk at the point of sale. It can also create additional backend income, improve product penetration, and offer a clearer value proposition than simply selling a vehicle and collecting a note.
For example, a vehicle payment reimbursement membership can help eligible customers when a covered event leaves the vehicle unusable. CPR For Cars is a non-insurance membership program built around that need, with car payment reimbursement and immediate travel and miscellaneous expense benefits under its program terms. For a BHPH dealer, the value is not limited to product revenue. The program can support payment continuity at the moment a customer is most likely to feel financially overwhelmed.
That distinction matters. A reserve helps the dealer after an account weakens. A relevant add-on may help the customer before financial stress turns into a missed payment, extension request, or avoidable default.
BHPH Add Ons Versus Reserves: The Core Difference
The simplest comparison is this: reserves absorb losses, while add-ons can be structured to produce income and reduce the pressure that contributes to losses.
That does not mean an add-on eliminates credit risk. No product should be presented as a guarantee against delinquency, repossession, or charge-off. Customers can still experience job loss, medical hardship, poor payment habits, or repair issues outside a product’s covered events. Dealers should never use product income as an excuse to underwrite weak deals or reduce prudent reserve levels.
Still, an add-on can change the economics of the deal in ways a reserve cannot. It may provide immediate gross profit, create a customer benefit that is easy for the sales team to explain, and help the dealership remain relevant after delivery. When the product also encourages customers to return to the selling dealer or service center, it can contribute to future repair revenue and retention.
The best strategy uses each tool for its purpose. Maintain reserves to protect against the losses you expect. Build an add-on menu to create profit and provide practical support when customer hardship threatens the account.
The Add-Ons That Belong in a BHPH Menu
Not every aftermarket product fits a BHPH customer or operating model. The product has to be understandable, useful, and affordable within the transaction. A long menu of vague protections can create confusion, slow down the delivery process, and raise compliance concerns. A focused menu gives the team confidence and gives customers a clearer choice.
Products are most likely to perform when they address one of four practical areas: vehicle repair exposure, payment disruption, transportation needs during a covered event, or ownership-related costs that can destabilize the customer’s budget.
Before adding any product, dealership leadership should ask whether the value can be explained in plain language. Can the customer understand what triggers the benefit? Are exclusions, eligibility requirements, cancellation rights, and claim procedures disclosed clearly? Does the payment fit the deal without pushing the customer beyond a reasonable monthly obligation?
If the answer is no, the product may create more friction than profit. BHPH dealers succeed with clarity. The customer should leave knowing what they bought, what it may help with, and how to use it.
Price for Value, Not for Maximum Markup
A high-margin product that causes buyer regret can create cancellations, complaints, and collection friction. A product with a clear benefit and sensible price has a better chance of staying on the contract and supporting customer satisfaction.
This is especially important in BHPH. The dealership has an ongoing relationship with the buyer, often for years. Unlike a one-time retail sale, the impact of an unhappy customer can show up in missed payments, service conflicts, negative reviews, and lost referrals. Protecting the customer experience protects the portfolio.
Train the Team to Sell the Outcome
Sales and F&I personnel should not present an add-on as a vague package or a last-minute payment increase. They should connect it to an ownership event the customer recognizes: “If your vehicle is unusable after a covered event, how would you handle your car payment and transportation costs?”
That conversation is direct, relevant, and respectful. It also keeps the team focused on benefits rather than pressure. Training should cover product terms, approved language, documentation, and how to avoid making promises the program does not make.
Measure the Portfolio Impact, Not Just Product Gross
Product penetration and per-unit revenue matter, but they do not tell the whole story. A BHPH dealer evaluating add-ons should track whether the program contributes to better customer outcomes and stronger portfolio performance over time.
Review cancellation rates, customer complaints, claim usage where available, delinquency trends, payment extension requests, repeat service visits, and customer retention. Compare results by vintage and by store if the operation has multiple locations. The goal is not to claim that one product caused every positive result. The goal is to identify whether the product is supporting the dealership’s larger financial strategy.
There is also a timing benefit. Reserves are generally funded after the dealership recognizes risk and performance trends. Add-on revenue is produced at origination, subject to the dealer’s accounting practices and any product-related obligations. That earlier revenue can strengthen per-deal economics, but it should be managed responsibly. Dealers still need to account for cancellations, refunds, chargeback exposure, and regulatory requirements.
Protect Profit Without Creating Compliance Risk
A profitable add-on program requires controls. Product documents must match the sales presentation. Payment terms must be disclosed accurately. If a product is optional, the customer must understand it is optional. Dealership personnel should never imply that approval, interest rate, vehicle availability, or future service depends on purchasing a membership or protection product unless that statement is factually accurate and permitted.
Management should also establish a clean process for cancellations and customer questions. A customer who needs help should not have to argue with the dealership to understand their benefit. Fast, consistent responses preserve trust and reduce unnecessary escalation.
This is where reserves and add-ons meet. Both are forms of business protection, but one is financial preparation and the other is a customer-facing program. Treat both with discipline. Maintain enough reserve to withstand real portfolio stress, then select add-ons that give customers a credible reason to remain current, loyal, and connected to your dealership.
The next time your team reviews portfolio losses, do not ask only how much should be set aside for the next problem. Ask what your dealership can offer that helps a customer stay on the road, stay engaged, and keep the payment relationship intact when trouble arrives.

Leave A Comment