A customer whose leased vehicle is disabled after a covered event is not thinking about their next lease yet. They are thinking about transportation, repair delays, and a payment that may still be due. That is where the lease loyalty program versus payment skip decision becomes more than an F&I menu question. It becomes a portfolio-performance decision.
Both concepts can support customer retention, but they solve different problems at different points in the lease lifecycle. A loyalty program motivates the next transaction. A payment skip option can offer short-term breathing room. Neither, on its own, directly addresses the financial strain that can arise when a customer cannot use the vehicle but still has a monthly obligation.
For lessors, lenders, and dealer groups, the stronger strategy is not simply choosing the benefit that sounds most attractive in a sales presentation. It is building an ownership experience that protects payment continuity, reinforces goodwill, and creates a credible reason for the customer to return.
Lease loyalty program versus payment skip: different jobs
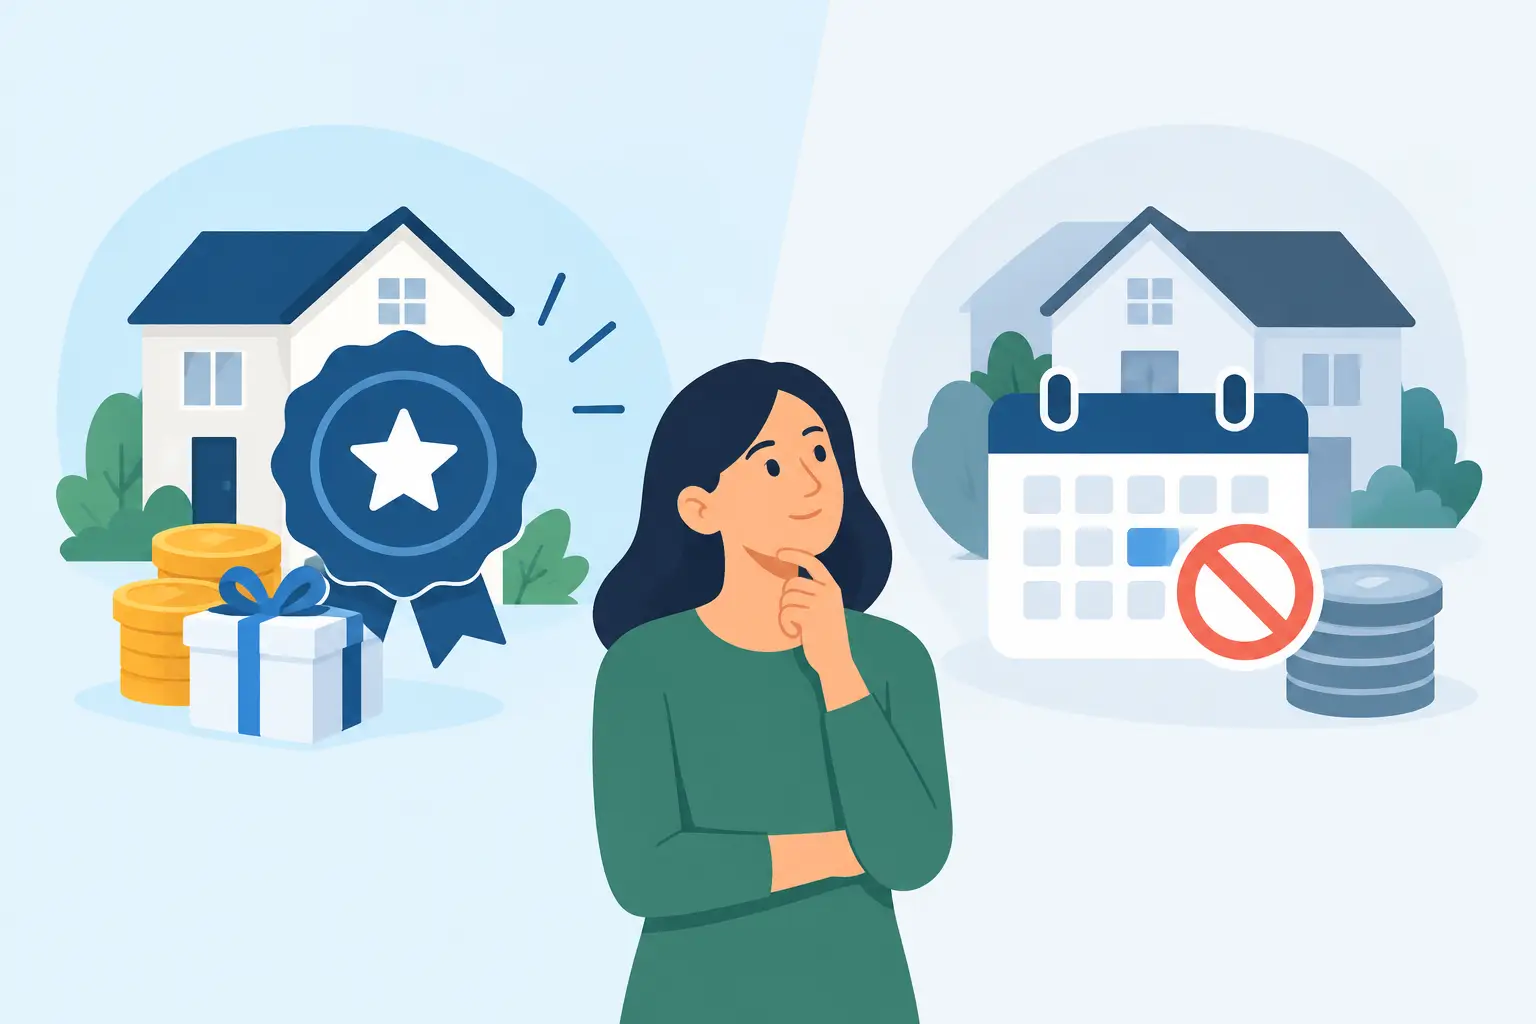
A lease loyalty program is generally designed to keep a customer within the same brand, dealer group, or captive finance relationship when their current lease ends. The offer may include a lease-end incentive, a renewal credit, waived disposition fees, or preferred pricing on the next vehicle. Its purpose is straightforward: reduce conquest risk and increase repeat business.
Payment skip, sometimes called payment deferral or payment extension, is a servicing accommodation. Depending on the contract and the provider’s policies, it may move a payment to the end of the term, extend the lease, or otherwise adjust the payment schedule. It can relieve immediate pressure, but it often does not eliminate the obligation. The customer may still owe the payment later, and the transaction can create additional operational and accounting considerations.
That distinction matters. Loyalty is an end-of-term retention tool. A payment skip is a short-term hardship response. Neither should be presented as a substitute for a product that helps customers manage a covered disruption while preserving normal payment behavior.
The gap between vehicle loss of use and payment due date
A disabled vehicle can quickly create two financial problems for a lessee. First, they need alternate transportation or funds for travel and incidental expenses. Second, their vehicle payment may remain due despite the vehicle being unavailable. A payment skip may address part of the second concern, subject to approval and program rules, but it does not put cash in the customer’s hands for the immediate disruption.
It can also change the customer’s perception of the relationship. If the only answer is to defer the bill, the customer may feel the problem has been moved rather than solved. For a customer already dealing with repairs, a collision, theft, or a total loss, that experience can damage the goodwill a loyalty program is meant to build.
A payment reimbursement membership is designed to fill this gap. When a covered event leaves the vehicle unusable, the customer can receive reimbursement for their monthly vehicle payment under the membership terms. That helps protect the customer from a disruptive expense at the moment the disruption occurs, rather than postponing the obligation to a later date.
Why payment continuity has commercial value
For a leasing company or lender, a missed payment is not just a customer-service issue. It can mean additional servicing activity, more difficult customer conversations, elevated delinquency exposure, and avoidable strain on the account relationship. For a dealership, it can reduce trust precisely when the customer needs a reason to return for their next vehicle.
A well-positioned reimbursement membership supports a more constructive outcome. The customer sees a tangible benefit when their vehicle is sidelined. The lessor or lender has a tool that can help preserve payment continuity. The selling dealer has an aftermarket product with a clear value story that extends beyond the day of delivery.
This is especially relevant for dealers and lessors that want to compete on more than rate, payment, or a standard lease-end offer. Most customers will not remember a generic promise of loyalty when they are stranded. They will remember who helped them manage a real financial setback.
Payment skip can be useful, but it has limits
There is a place for payment skips and extensions. A customer facing a temporary hardship may need flexibility, and a properly administered option can help preserve the relationship. The key is to be clear about what the accommodation does and does not do.
If a skipped payment is deferred, the obligation typically remains. The customer may face a longer term, a larger final obligation, or other conditions based on the lease agreement and servicing policy. That is not necessarily a bad outcome, but it is different from reimbursing a payment after a covered loss-of-use event.
From an operational standpoint, payment skips can also require case-by-case review, servicing approvals, disclosures, and consistent policy administration. They are reactive by nature. A membership sold at origination gives the customer a defined protection benefit before the disruption happens and gives the finance team a more proactive value proposition.
The best approach may include both tools. A payment skip can remain available for broader hardship situations, while payment reimbursement handles the specific financial shock of a covered event that makes the vehicle unusable. The programs serve different needs, and treating them as interchangeable can leave a meaningful protection gap.
Build loyalty before the lease-end conversation
Loyalty programs work best when they reinforce an existing positive customer experience. If a customer received meaningful help during an unexpected vehicle event, a renewal offer arrives in a much warmer relationship. The customer is not simply comparing monthly payments. They are evaluating whether the dealer group, lessor, or finance partner delivered when it mattered.
That is why protection benefits can strengthen lease retention indirectly but powerfully. They create a service moment that a traditional lease loyalty incentive cannot create on its own. The customer has a reason to stay connected to the provider that helped them maintain financial stability during a difficult period.
For dealership partners, this can also support service-center return traffic. When the customer is working through a repair-related event, the dealership has more opportunity to remain part of the ownership experience instead of becoming a distant point of sale. A stronger service relationship supports future sales, future F&I opportunities, and residual business.
A better product conversation for F&I and leasing teams
The sales message should be simple: a lease payment does not always stop just because the vehicle does. Customers understand that immediately. The conversation can then focus on the practical value of protection when a covered event interrupts vehicle use.
CPR For Cars gives partners a differentiated, non-insurance membership they can offer as an additional source of revenue and customer support. The program reimburses a monthly car payment when a covered event leaves the vehicle unusable. It also provides up to $500 for immediate travel and miscellaneous expenses during the first year, plus up to $1,000 toward a replacement vehicle after a total loss based on the customer’s original down payment with the dealer.
For a lease operation, those benefits create a more complete response than a future lease-end reward or a deferred payment alone. The customer gets potential financial relief at the point of disruption. The partner gains a monetizable product that supports retention and helps safeguard the portfolio.
What decision-makers should evaluate
When comparing a loyalty offer, a payment skip policy, and a reimbursement membership, start with the customer scenario each one is built to address. A loyalty incentive answers, “Why should I lease here again?” A payment skip answers, “Can my due date be adjusted?” Payment reimbursement answers, “How can I keep up when a covered event takes my vehicle out of service?”
Then evaluate the business outcome. Does the offering create backend revenue? Can it support more consistent payment behavior? Does it give the dealership a meaningful ownership benefit that separates it from nearby competitors? Can the team explain it clearly without creating confusion about insurance, repairs, or loan modifications?
The answer will vary by portfolio, customer base, and servicing model. A captive lease program may emphasize renewal conversion. A BHPH operator may place greater weight on payment stability. An independent dealer group may prioritize F&I gross and customer return traffic. But every model benefits from giving customers a practical answer when their vehicle becomes unusable.
The strongest loyalty strategy is earned long before a customer begins shopping for their next vehicle. Give them a reason to remember how your organization protected them when the payment still mattered and the vehicle could not move.

Leave A Comment